
SHEIN will finally go public, listing in Hong Kong on August 31, but at a valuation of $27 billion that is a fraction of the PitchBook indicated post-market valuation of $66 billion in 2023. We think the decline in market perception of SHEIN reflects slower revenue growth amid a slew of geopolitical challenges as well as increased competition. While sales in Asia are helping to offset a fall in US revenue, we’re probably looking at a period of single-digit revenue growth for the company and this maturing outlook is likely to limit investor excitement. On top of this, tariff and other geopolitical risks remain.
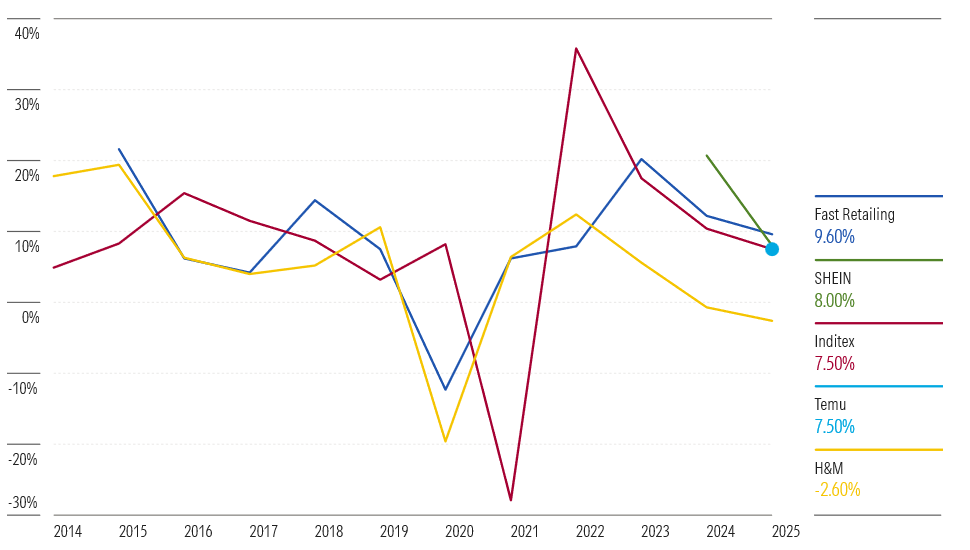
Data prior to 2023 is not publicly available for SHEIN but it would appear that revenue growth has converged to the pace seen by the fast fashion industry at below 10% in 2025. We forecast the fast fashion industry’s leaders, Fast Retailing and Inditex, will track an average three-year revenue growth of 11% and 7% respectively. Fast Retailing is benefiting from a recovery and expansion in its US and European sales from a low base. We therefore would not be surprised if SHEIN’s revenue growth hovers around the current 7.5% pace over the next three years especially after the change in de minimis policies and tariffs have raised the average cost of items sold in the US, which is a key market.
Chart 1: SHEIN’s Revenue Growth is Converging to Broad Industry Pace
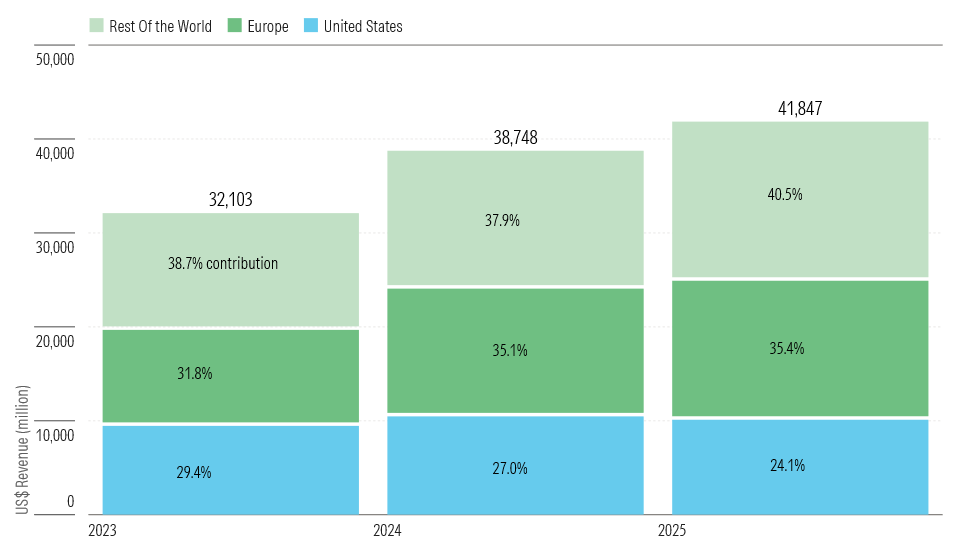
Revenue from the US fell 3.5% in 2025, which is not surprising given the tariff uncertainties last year. As a result, the US, as a share of SHEIN’s sales, declined to 24.1% from 29.4% between 2023 and 2025. Currently, growth outside the US and Europe is more than making up for the shortfall. But with Europe recently introducing a flat EUR 3 tax on purchases below EUR 150, we could see some pressure on European sales. We would not be surprised if US and European sales only keep pace with the rate of inflation over the next few years. If so, SHEIN would need to maintain its 15% revenue growth in the rest of the world to achieve an average revenue growth rate of around 7.5% over three years
Chart 2: The US’s Share of SHEIN’s Revenue is Falling
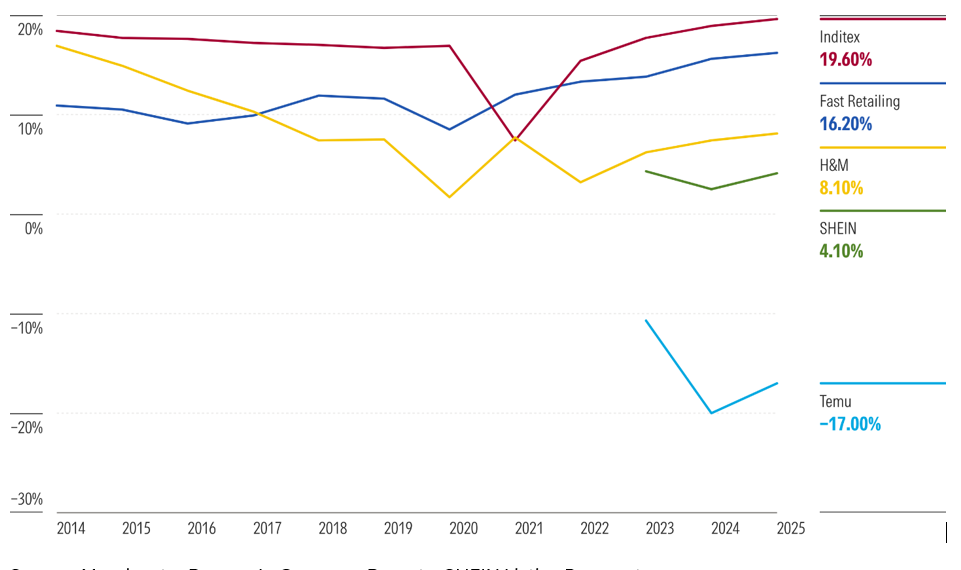
On top of the slowing revenue growth outlook, an even greater challenge could be the pressure on operating margins. While SHEIN’s revenue growth may keep track with its fast fashion peers, its operating margin is notably lower, at just 4.1% in 2025. We think this reflects the lower selling price and overall purchase value of SHEIN’s products. Therefore, SHEIN needs to be able to pass through rising costs. This becomes more of a challenge in the face of the additional tax in Europe and following the removal of the de minimis exemption. This implies that if SHEIN wants to grow its revenue and maintain operating leverage, raising prices will lag higher costs. Furthermore, we expect competition to remain intense so customer acquisition costs are likely to remain high. Additionally, there is no indication that Temu will ease back on its market share push and this presents another challenge to SHEIN as well.
Chart 3: SHEIN’s Adjusted Operating Margin is Well Below Fast Fashion Industry’s Leaders
On the bright side, SHEIN is financially well positioned to weather its current hiccups. The company is in a net cash position and does not really need to list although it mentions that the capital raised from the listing will be used for expansion. We suspect that the listing enables some private equity investors to exit their investment in SHEIN.
However, the fall in valuation does reflect that drop off in investor appetite for SHEIN’s shares. We believe this largely reflects the more pedestrian growth outlook for the near term. SHEIN is trying to evolve its business model to include more service revenue, where it charges third-party merchants to complete their sales transactions. But the key determinant of the company’s valuation will still rest on its ability to sell goods.
